“Observability is evolving from a system of record for technology operations into a system of intelligence for business resilience.”
In the first two parts of this series, we explored how observability is evolving beyond traditional monitoring and how Business Observability is helping banks connect technology performance with customer and business outcomes.
The next phase of this evolution is already beginning.
Increasingly, observability is becoming a foundational capability for operational resilience, AI-assisted operations, and the future operating model of technology organizations.
This shift is being driven by a simple reality.
Banking systems have become too complex for humans alone to fully understand in real time.
Banking Has Entered the Era of Continuous Operations
A generation ago, banks operated largely within defined business hours.
Batch processing occurred overnight. Customer interactions were concentrated around branches. Technology environments were relatively predictable.
Today’s environment looks very different.
Customers expect banking services to be available at any time, from anywhere, through any channel.
- Payments happen in real time
- Digital channels operate continuously
- Partner ecosystems exchange information constantly
- Cloud platforms dynamically scale infrastructure
- Technology teams deploy changes more frequently than ever before
The modern bank is effectively a 24×7 digital enterprise.
In such environments, operational disruptions are no longer isolated technology events. They can quickly become customer experience issues, revenue-impacting incidents, reputational concerns, or regulatory challenges.
This is why operational resilience has become a board-level topic across the financial services industry.
Availability Is No Longer Enough
Historically, technology organizations focused heavily on availability. The primary objective was to keep systems running.
Availability remains important, but it is no longer sufficient.
A service may be technically available while still failing to deliver an acceptable customer experience.
A payment application may be online while transaction success rates decline.
A mobile banking platform may remain operational while response times increase significantly.
A lending system may continue processing requests while approval turnaround times deteriorate.
In each case, the service is available, yet the business outcome is compromised.
Operational resilience introduces a broader perspective.
The question is no longer: “Is the system available?”
The question becomes: “Can the organization continue delivering critical business services despite failures, disruptions, or unexpected conditions?”
This distinction is subtle but significant. It shifts attention from individual systems toward end-to-end business capabilities.
Understanding Resilience Through Dependencies
One of the most challenging aspects of modern banking environments is the growing web of dependencies.
A customer payment may depend upon:
- Mobile applications
- Authentication services
- API gateways
- Fraud management platforms
- Payment switches
- Core banking systems
- External payment networks
- Cloud infrastructure
- Telecommunications providers
A disruption in any one component can affect the entire customer journey.
What makes the challenge even more difficult is that failures do not always originate within the bank itself.
Many critical services depend upon third-party providers, SaaS platforms, cloud infrastructure, fintech integrations, and ecosystem partners.
As these dependencies increase, visibility becomes increasingly important.
Organizations need to understand not only whether individual systems are functioning, but also how failures propagate across interconnected services.
This is one of the areas where observability is beginning to play a much broader role.
Observability as a Foundation for Operational Resilience
Observability platforms were originally designed to help engineers troubleshoot technology problems.
Today, they are increasingly being used to provide organizational awareness.
In many ways, observability is becoming the nervous system of modern digital enterprises.
It provides continuous insight into:
- Service behavior
- System interactions
- Dependency relationships
- Operational anomalies
- Customer impact
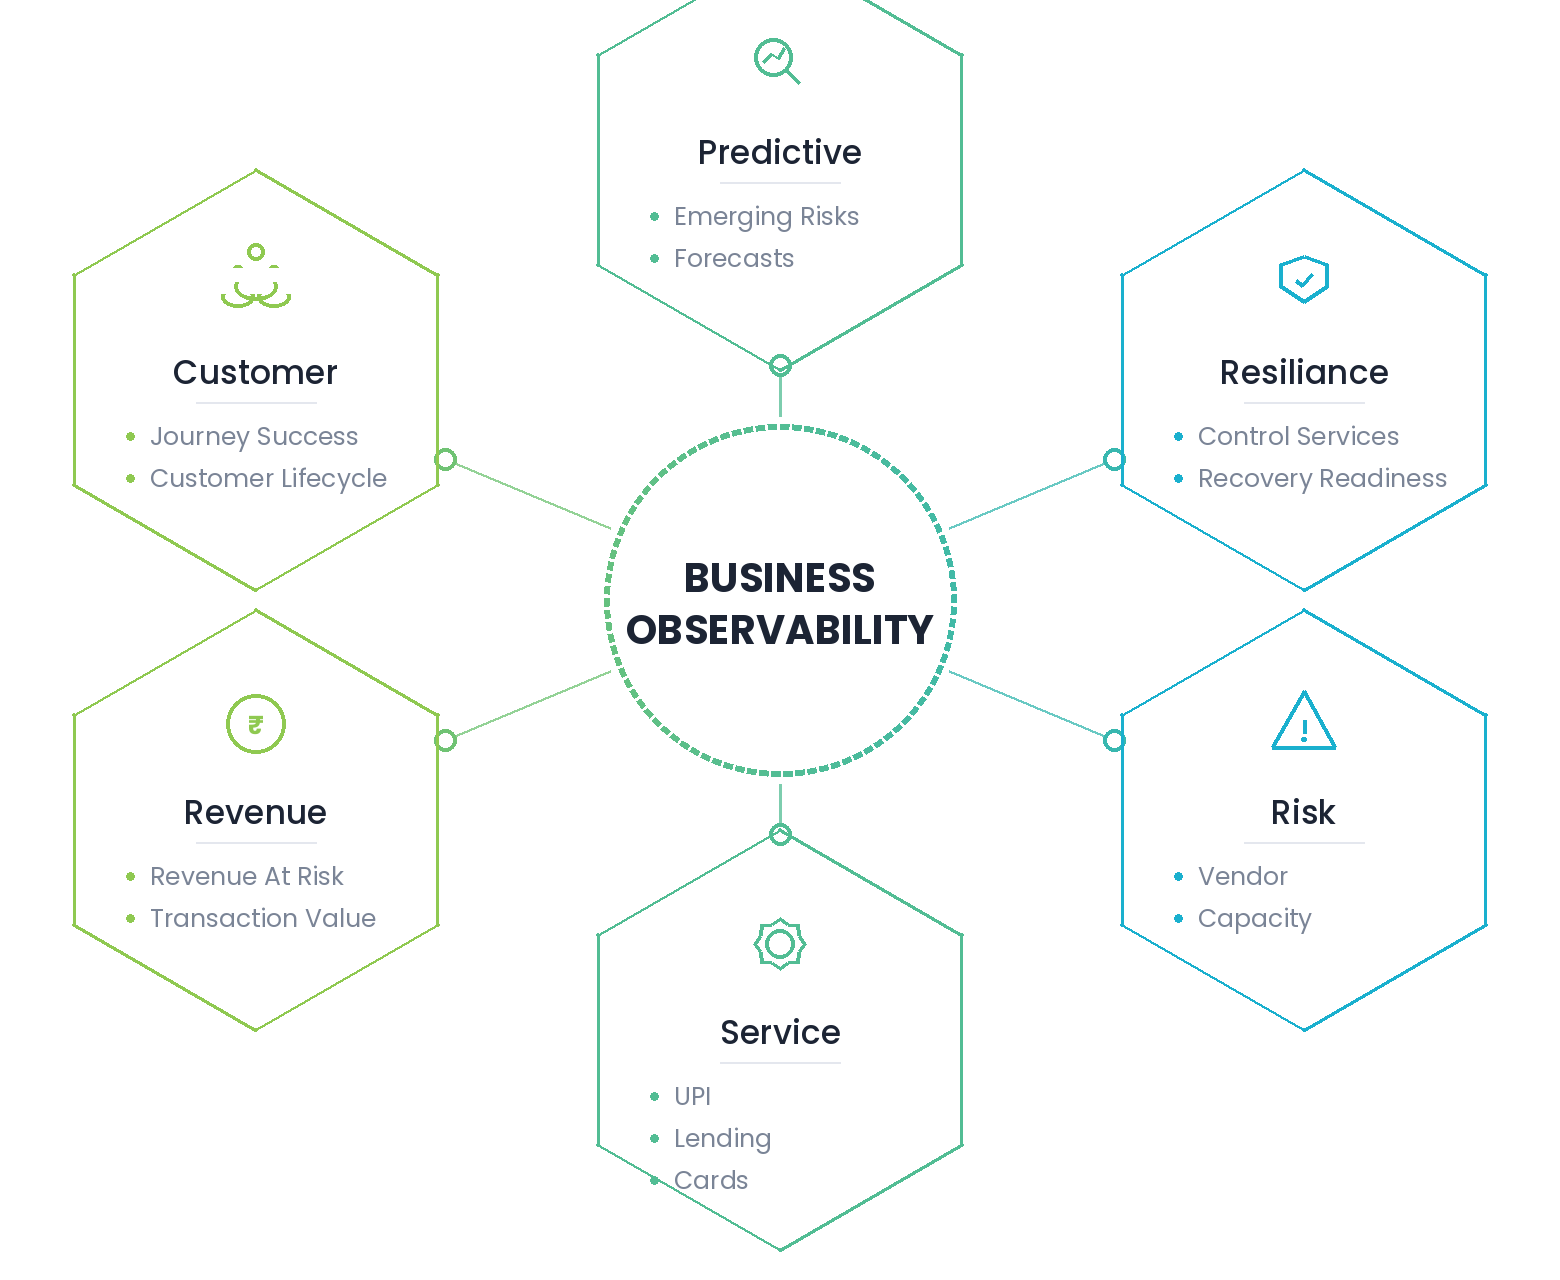
- Emerging risks
This visibility enables organizations to detect changes earlier and respond more effectively.
Rather than discovering problems after customers complain, teams can identify signals that indicate service degradation before major incidents occur.
Rather than focusing solely on technical alerts, organizations can understand which business services are affected and which customer journeys are at risk.
The result is a more proactive approach to resilience.
The Growing Importance of Early Warning Indicators
Many significant outages do not begin as outages. They begin as small deviations from normal behavior.
- A slight increase in latency
- A growing queue backlog
- An unusual error pattern
- A slow decline in transaction success rates
- A dependency becoming progressively unstable
Individually, these signals may appear insignificant. Collectively, they often represent early warning indicators of larger issues.
Historically, identifying these patterns required highly experienced engineers manually correlating information from multiple systems.
As environments continue to grow, this approach becomes increasingly difficult to sustain.
Organizations are therefore placing greater emphasis on detecting trends, anomalies, and emerging risks before they become business-impacting incidents.
This is where observability and AI are beginning to converge.
The Role of AI in Modern Operations
Modern banking environments generate enormous volumes of telemetry.
Logs, metrics, traces, events, alerts, customer interactions, infrastructure data, and application signals collectively create a vast operational dataset.
The challenge is no longer collecting information. The challenge is understanding it.
AI is becoming increasingly important because it can help organizations process information at a scale that exceeds human capability.
The objective is not to replace operations teams. The objective is to augment them.
Several use cases are already emerging.
Incident Summarization
During major incidents, engineers often spend valuable time gathering information from multiple systems. AI can help summarize relevant events, affected services, probable impact areas, and recent changes. This reduces investigation time and helps teams establish context more quickly.
Event Correlation
Large organizations routinely generate thousands of alerts. Many of these alerts are symptoms rather than root causes. AI can assist in identifying relationships between events and grouping related signals into meaningful incidents. This helps reduce noise and improve focus.
Dependency Analysis
Modern service architectures often contain hundreds or thousands of dependencies. Understanding how services interact can be difficult. AI can help identify dependency relationships and estimate the potential impact of failures. This supports faster decision-making during incidents.
Root Cause Investigation
Root cause analysis frequently requires engineers to search across logs, metrics, traces, configuration changes, and deployment histories. AI can assist by identifying patterns and narrowing the investigation scope. The final determination remains a human responsibility, but the investigative process becomes significantly more efficient.
The Journey Toward Autonomous Operations
Observability and AI together are enabling a broader evolution in technology operations.
A useful way to view this progression is through five stages of maturity.
| Stage |
What it delivers |
Objective |
| 1. Monitoring |
Infrastructure visibility |
Detecting failures |
| 2. Observability |
Deeper visibility into applications, services, and distributed architectures |
Understanding system behavior |
| 3. Business Observability |
Technical telemetry connected to customer journeys and business outcomes |
Understanding business impact |
| 4. Predictive Operations |
Trends, anomalies, and emerging risks identified before incidents occur |
Anticipating problems |
| 5. Autonomous Operations |
Automated detection, diagnosis, remediation, and optimization |
Reducing operational effort while improving resilience |
Most banks today are somewhere between stages two and three.
Over the next several years, many are expected to move toward predictive operations.
The transition toward autonomous operations will likely occur gradually, driven by improvements in AI capabilities, operational maturity, governance frameworks, and organizational confidence.
What This Means for Banking Leaders
For technology leaders, observability is no longer simply an operational toolset.
It is becoming a strategic capability that supports three important objectives.
Better Customer Outcomes
By understanding customer journeys and business services in real time, organizations can improve digital experiences and reduce customer impact during disruptions.
Stronger Operational Resilience
By improving visibility into dependencies, risks, and emerging issues, organizations can strengthen their ability to withstand operational disruptions.
More Intelligent Operations
By combining observability with AI and automation, organizations can improve efficiency, reduce manual effort, and accelerate decision-making.
These objectives extend well beyond traditional monitoring.
They influence how technology organizations are structured, how risks are managed, and how digital services are delivered.
Looking Ahead
The future of observability is unlikely to be defined by dashboards alone.
It will increasingly be defined by the quality of decisions that organizations can make using the information available to them.
As banking ecosystems become more distributed, more interconnected, and more dependent upon digital services, the ability to understand operational behavior in real time will become increasingly important.
Observability is evolving from a troubleshooting capability into a business capability.
It is helping organizations understand not only what is happening, but also why it matters and what should happen next.
In that sense, observability is becoming one of the foundational building blocks of resilient, intelligent, and increasingly autonomous banking operations.